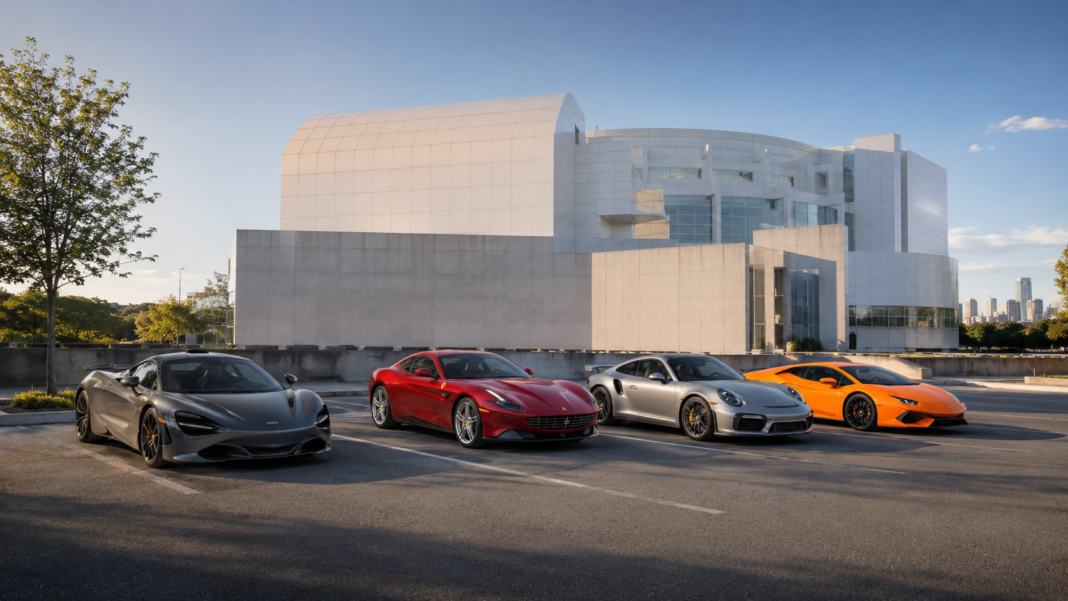
The morning light filters through the glass atrium of the High Museum of Art in Atlanta, Georgia. The building itself is a work of art, designed by Richard Meier and Renzo Piano. In the parking lot, a collection of supercars is gathered. A McLaren 720S, a Ferrari Roma, a Porsche 911 Turbo S, and a Lamborghini Huracán EVO. Their owners are not here to talk about horsepower. They are here to compare insurance policies.
Supercar insurance is different from standard car insurance. Agreed value, market value, track day coverage, mileage restrictions, storage requirements. The terminology is confusing, and the consequences of a mistake can be catastrophic.
This guide covers everything you need to know about supercar insurance in 2026. The advice comes from a specialty insurance broker who has placed policies on over $100 million worth of exotic cars.
The Location: High Museum of Art, Atlanta, Georgia
Atlanta is a hub of wealth and car culture. The city has multiple Ferrari, Lamborghini, and McLaren dealerships. The owners here are educated, wealthy, and careful. They have learned through experience which insurers are reliable and which are not.
Agreed Value vs. Market Value: The Most Important Decision
The single most important decision you will make is choosing between agreed value and market value.
Agreed value: You and the insurer agree on a specific value for the car at the start of the policy. If the car is totaled, you receive that agreed amount. There is no negotiation, no depreciation argument, no haggling.
Market value: The insurer pays what the car is worth at the time of the loss, based on current market data. This amount may be less than what you paid, less than what you owe, and less than what it would cost to replace the car.
For supercars, agreed value is the only sensible choice. Supercar values fluctuate, and some models appreciate. A market value policy could leave you with a significant shortfall.
The broker’s advice: “Always get agreed value. Document the car’s condition, mileage, and provenance. Update the agreed value annually.”
Mileage Restrictions: How Much Can You Drive?
Supercar policies typically have annual mileage limits. Common limits are 1,000, 3,000, or 5,000 miles per year. Some insurers offer unlimited mileage policies, but they are expensive.
If you exceed your mileage limit, the insurer may refuse to cover a claim. Do not guess. Be realistic about your annual driving.
The broker’s advice: “Estimate your annual mileage honestly. If you drive 4,000 miles per year, do not buy a 3,000 mile policy. The savings are not worth the risk.”
Storage Requirements: Where the Car Must Sleep
Most supercar insurers require the car to be stored in a locked, enclosed garage. Street parking is not acceptable. Some insurers also require a security system and a fire extinguisher.
If you live in an apartment or condo, verify your parking situation before you buy a policy. A shared garage may not meet the insurer’s requirements.
The broker’s advice: “Take photos of your garage. Document the locking mechanism, the security system, and the condition. Send them to your insurer when you apply.”
Track Day Coverage: Can You Drive on a Circuit?
Many supercar owners want to track their cars. Standard policies exclude track use. If you crash on a racetrack, even during a non-competitive driver education event, your claim will be denied.
Some insurers offer track day endorsements. These provide coverage for specific events at specific tracks. The coverage is limited, and the deductible is higher.
The broker’s advice: “If you plan to track your car, buy a policy with a track day endorsement. Read the fine print. Some policies only cover driver education events, not timed laps or competitions.”
The Insurers That Understand Performance Cars
Not all insurance companies understand supercars. A standard insurer may not know how to value a rare Ferrari or how to source a replacement part.
Specialty insurers focus on exotic and high performance cars. They understand the market, the repair process, and the needs of supercar owners.
The broker recommends these companies:
- Chubb: Excellent for high net worth individuals with large collections. Agreed value, worldwide coverage, and low deductibles.
- Hagerty: The best known specialty insurer. Agreed value, track day options, and a community of enthusiasts. Good for cars driven fewer than 5,000 miles per year.
- Grundy: Similar to Hagerty. Agreed value, no mileage limits for pleasure driving, and reasonable rates. Not available in all states.
- Pure: A high net worth insurer. Excellent service, agreed value, and bundled policies for home, auto, and umbrella.
The broker’s advice: “Do not use a standard insurer like Geico, Progressive, or State Farm for a supercar. They do not understand agreed value. They will fight you on a claim.”
The Cost: What to Expect
Supercar insurance costs vary widely based on the car’s value, your driving record, your location, and your annual mileage.
- Porsche 911 Carrera (agreed value $120,000): $2,000 to $3,000 per year
- McLaren 720S (agreed value $180,000): $4,000 to $6,000 per year
- Ferrari 488 GTB (agreed value $190,000): $4,500 to $7,000 per year
- Lamborghini Aventador (agreed value $400,000): $8,000 to $12,000 per year
Younger drivers, drivers with tickets or accidents, and drivers in urban areas pay more.
The Atlanta Conversation: Real Owners, Real Policies
The owners at the High Museum are sharing their experiences.
A McLaren 720S owner says, “I use Hagerty. I have an agreed value of $180,000. I pay $5,200 per year. I have a 3,000 mile limit. I have never had a claim.”
A Ferrari Roma owner says, “I use Chubb. I bundle my car with my home and umbrella policies. I pay $4,800 for the car. The service is excellent.”
A Porsche 911 Turbo S owner says, “I used to use a standard insurer. They tried to pay me market value after a minor accident. The repair cost was $15,000. They offered $9,000. I switched to Grundy the next week.”
The Claim Process: What Happens When You Crash
Filing a claim on a supercar is different from filing a claim on a Honda Civic. The insurer will send an adjuster who specializes in exotics. The repair shop must be approved and experienced with carbon fiber and aluminum structures.
The process is slower. Parts may need to be sourced from Italy, Germany, or England. The repair may take months.
The broker’s advice: “Document everything. Take photos of the damage, the scene, and the other vehicles. Keep receipts for towing and storage. Do not authorize repairs until the insurer has approved the estimate.”
The First-Time Buyer’s Checklist
Before you insure a supercar, complete this checklist.
- Choose agreed value over market value.
- Document the car’s condition with photos.
- Estimate your annual mileage honestly.
- Secure a locked, enclosed garage.
- If you track the car, buy a policy with a track day endorsement.
- Work with a specialty insurer, not a standard insurer.
- Compare quotes from Hagerty, Grundy, Chubb, and Pure.
- Read the fine print. Understand your deductible, your mileage limit, and your storage requirements.
The High Museum Afternoon
The owners have finished their coffee. They are walking back to their cars. The McLaren owner is checking his tire pressure. The Ferrari owner is wiping a smudge off the door. The Porsche owner is adjusting his mirrors.
They are not worried about insurance. They did their homework. They chose the right policies. They drive their cars. They enjoy their cars.
The broker’s final advice: “Insurance is not exciting. It is not sexy. But it is the most important part of supercar ownership. Do not skip the research. Do not cheap out. Protect your investment.”
Conclusion
Supercar insurance is complex, but it is not impossible. The key is understanding agreed value, mileage restrictions, storage requirements, and track day coverage. Work with a specialty insurer that understands exotic cars. Document everything. Read the fine print.
The High Museum is quiet now. The supercars are gone. The owners are driving home, protected by policies that fit their needs.
That is the goal of supercar insurance. Not to be the cheapest. To be the right coverage when you need it most. Do your homework. Protect your dream.

